Throughout this narrative, italicized and underlined texts are links to supporting documents.
Many owners in Tower 500 are aware that a mystery surrounds the Roof Replacement Project: How did a $232,638.00 deduction from the contract with Best Roofing become a payment to Best Roofing for the identical amount? And was it really an error, as claimed by both Management and the Board?
OUR CONCLUSION: THE DOCUMENTED RECORD RAISES SERIOUS QUESTIONS THAT THE CLAIM OF A SIMPLE ERROR DOES NOT ANSWER.
As readers examine the documents and follow the chronology presented on this page, the explanation offered by the Board and Management becomes increasingly difficult to reconcile with the documented record. The records show a $232,638.00 deduction from the contract with Best Roofing, followed by a payment request and an actual payment recorded for that exact same amount. They also raise questions about the approvals, accounting entries, and subsequent explanations surrounding the transaction.
How did a contractual deduction become a payment for the identical amount? Why was the payment processed and recorded as it was? What documentation establishes that the payment was voided or returned, and how was the transaction ultimately reconciled in the Association’s financial records?
These are questions every owner should be asking after reviewing the evidence presented here. The documented sequence of events warrants a clear, complete, and verifiable explanation of what happened and how the Association’s funds were accounted for.
The following account is based primarily on records obtained from Castle Group’s CastleClick payment portal, together with related documents and statements.
1. The Deduction — Followed by a Payment Request
On January 3, 2025, Change Order No. 4, submitted by Falcon Engineering, reduced the Best Roofing contract by $232,638.00.
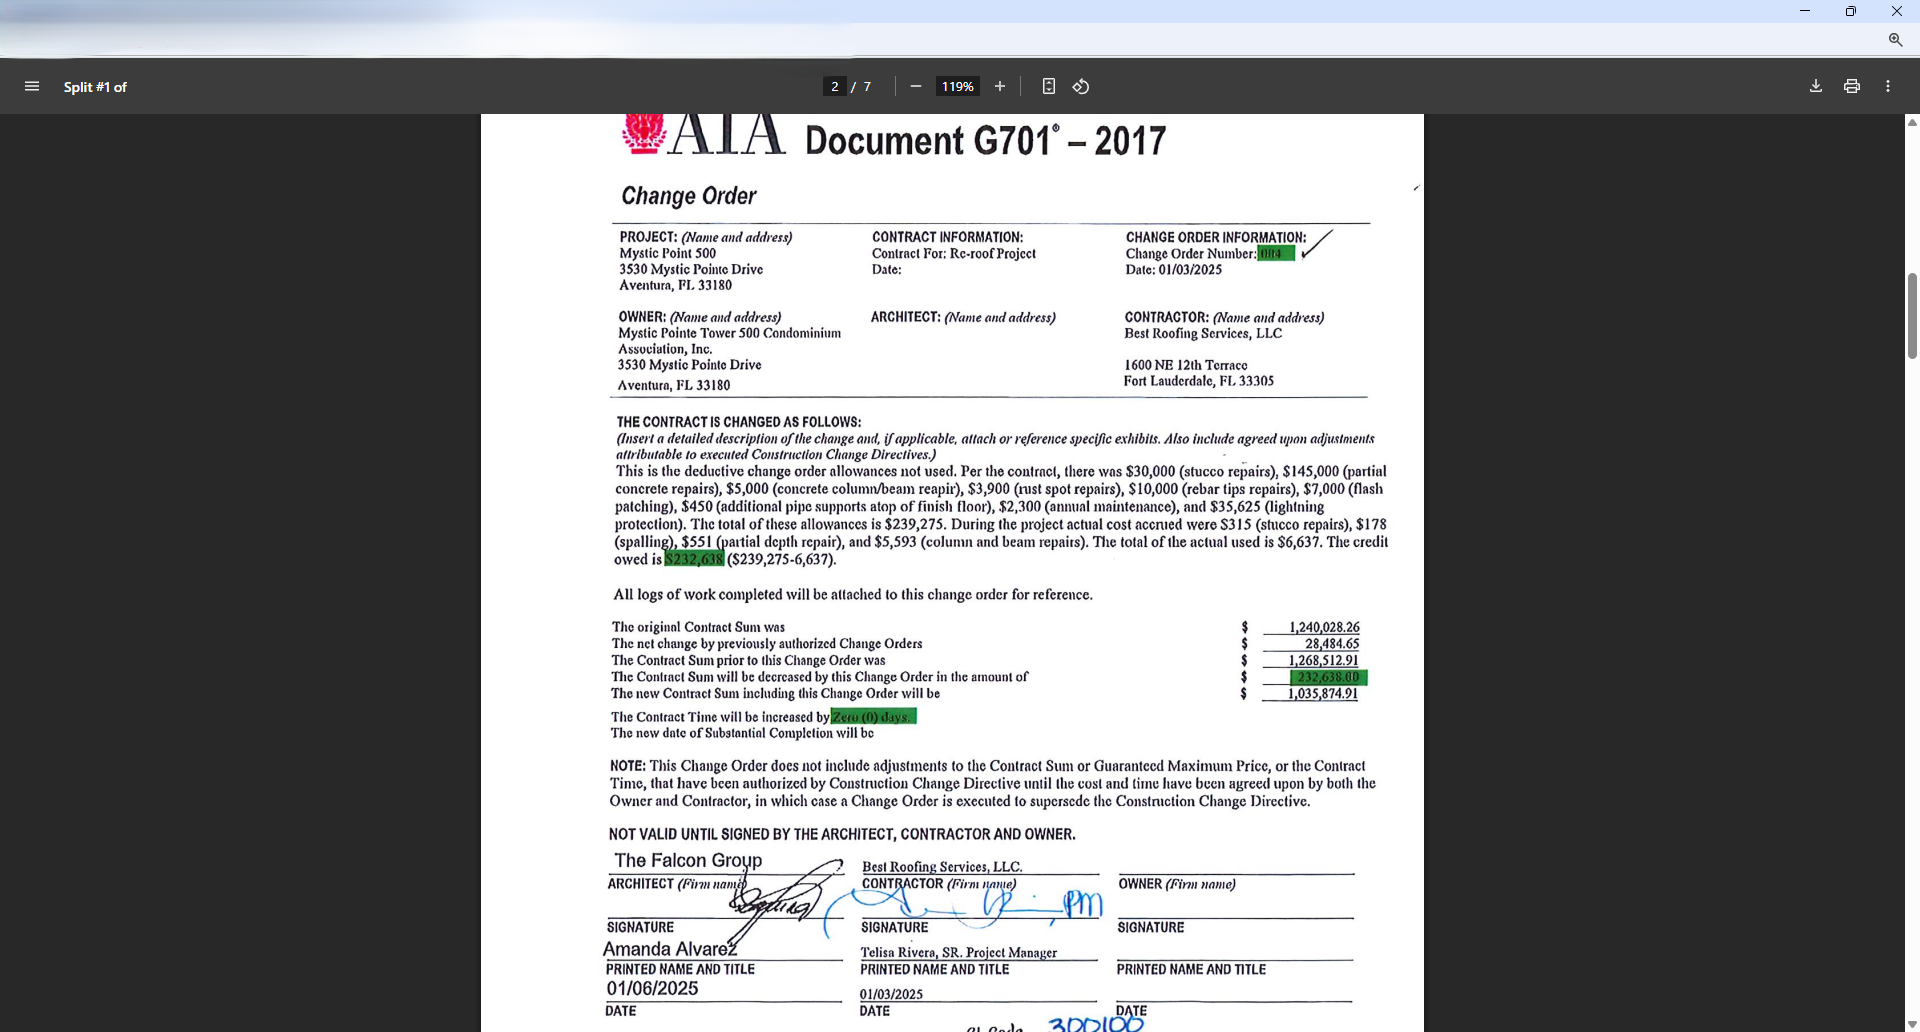
The change order identified $239,275 in allowances for work included in the contract but not performed, less $6,637 in actual costs for work that had been performed. The resulting $232,638.00 was a credit to the Association.
The change order stated that the contract sum was reduced from $1,268,512.91 to $1,035,874.91.
Seven days later, on January 10, 2025, a Check Request was prepared payable to Best Roofing for that exact same $232,638.00. It was eventually signed by Property Manager Michael Alvira and his assistant Helen Martinez.
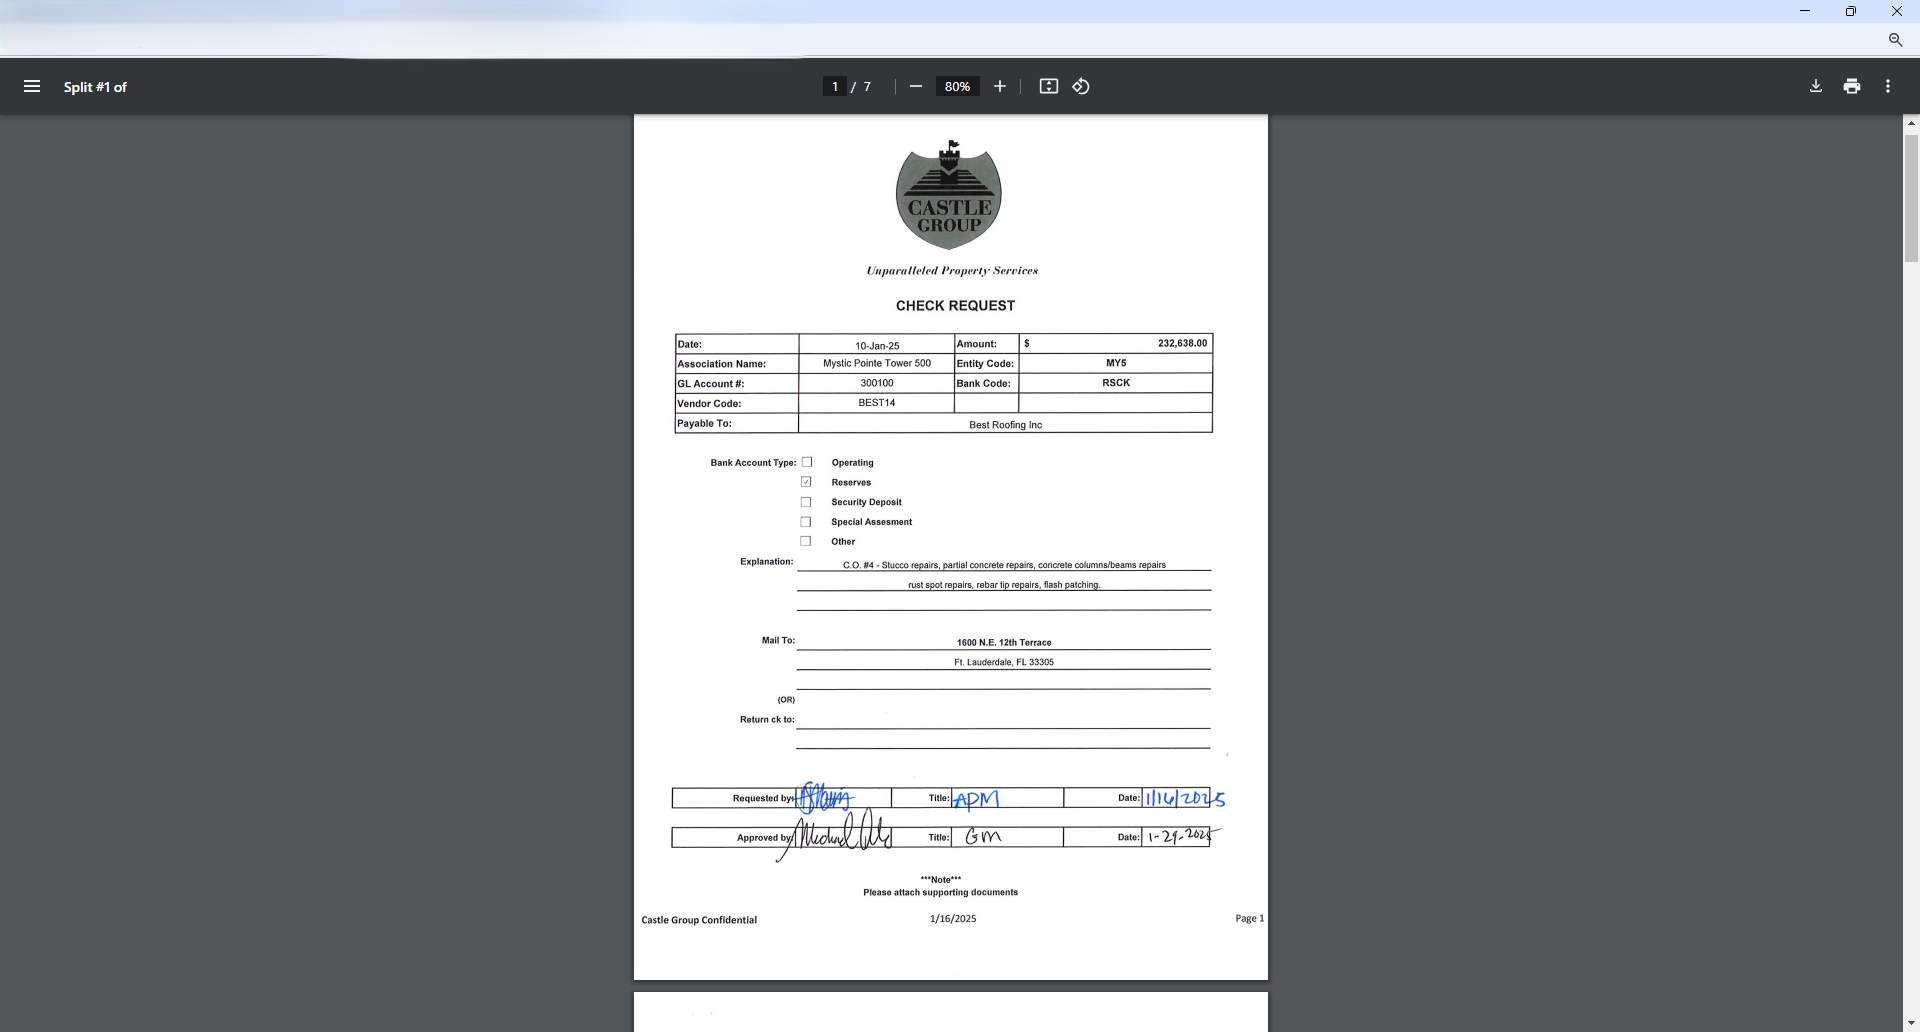
The request referred to Change Order No. 4 and listed roofing items as the reason for the payment. Those same items appeared in the change order as work included in the contract but not performed.
The contradiction is direct: the change order reduced the amount payable under the contract, yet the subsequent Check Request sought payment to Best Roofing for the same amount.
What an actual payment application shows
Best Roofing’s January 31, 2025, final Application for Payment, using AIA forms G702/G703, incorporated the change order and showed a current payment due of $124,272.72.
Falcon approved that amount on February 14. Following approvals by Property Manager Michael Alvira, Board President Stewart Glass, and Treasurer Karen Madsen, the $124,272.72 payment was made on February 28.
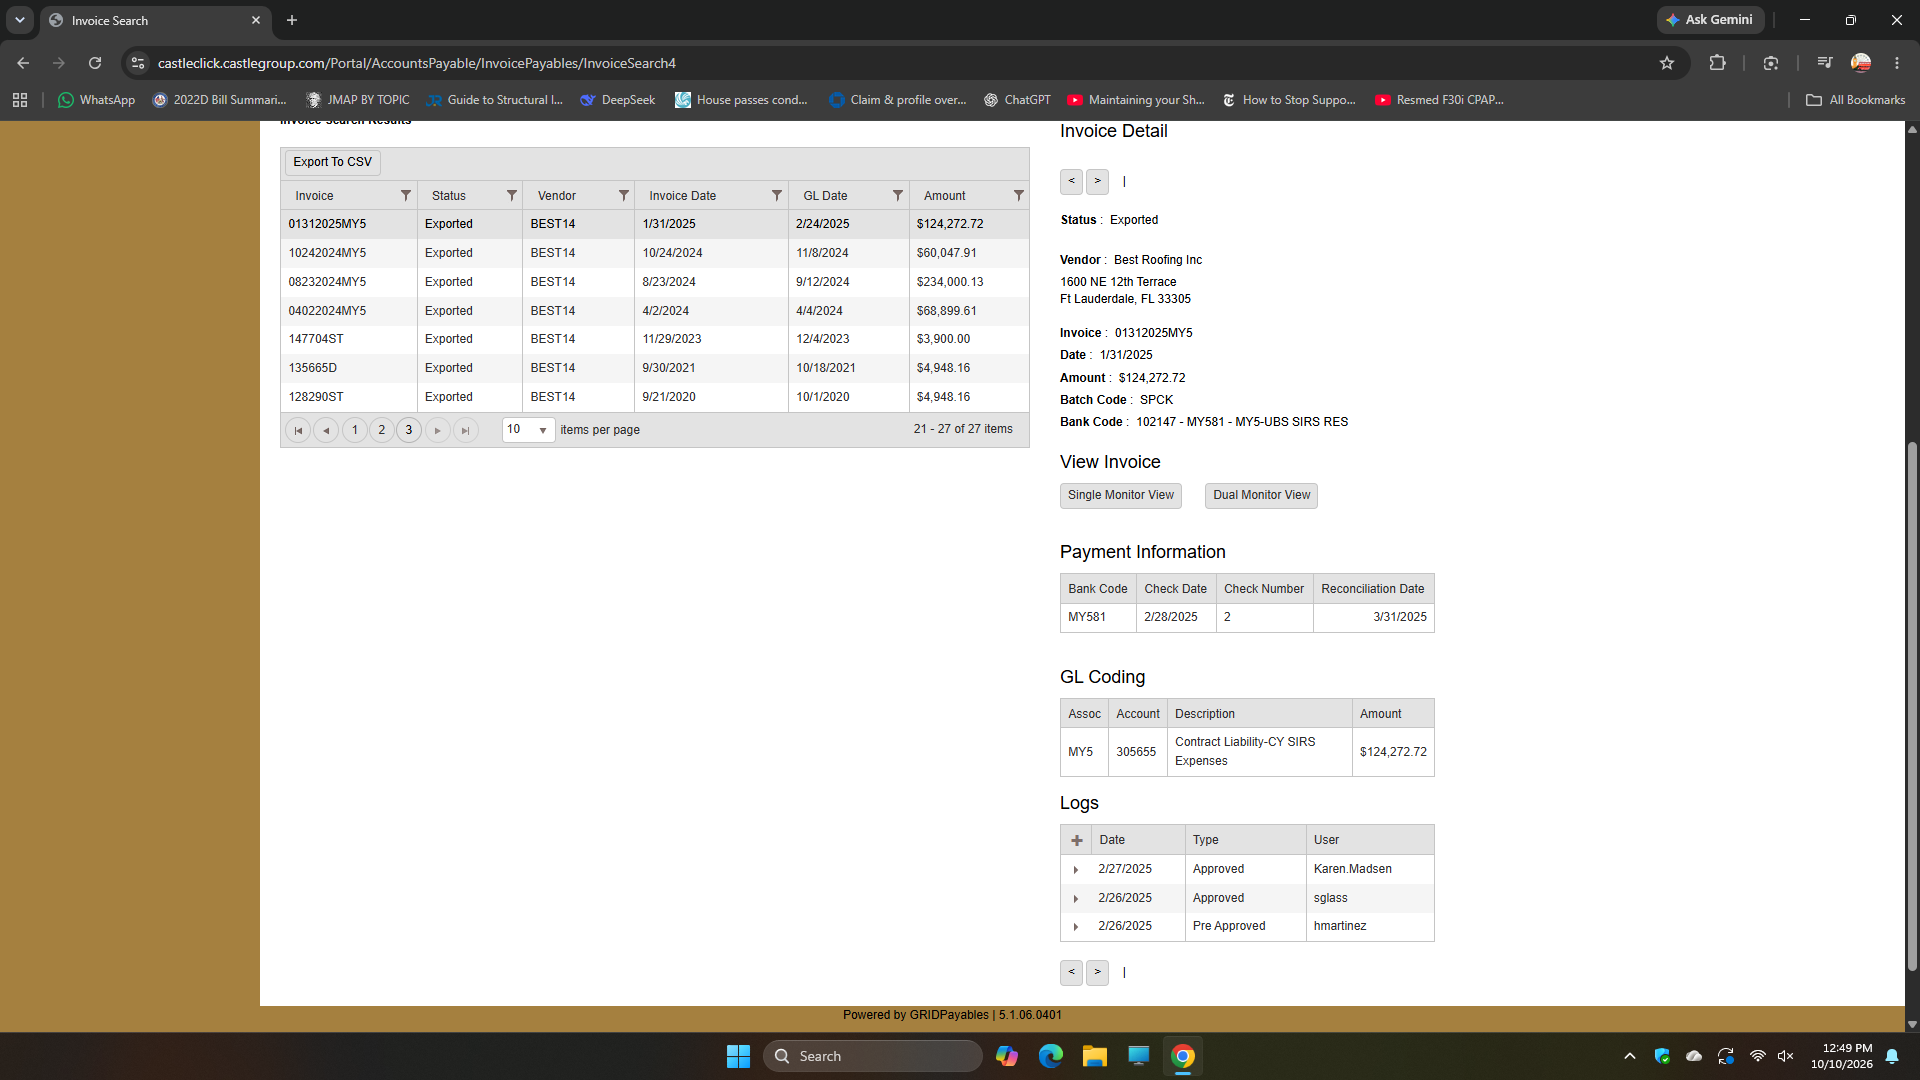
The $124,272.72 payment is distinct from the $232,638.00 check. The former was supported by a payment application; the latter arose from a Castle Group Check Request.
2. The Approval Trail and Accounting Treatment
The $232,638.00 Check Request did not proceed directly from preparation to issuance. CastleClick records show the following sequence:
- January 10: Check Request prepared.
- January 16: Signed by Assistant Property Manager Helen Martinez.
- January 29: Signed by Property Manager Michael Alvira.
- January 31: Martinez’s approval record shows the transaction as pre-approved.
- February 3: Approved by Treasurer Karen Madsen.
- February 10: Approved by Board President Stewart Glass.
- February 26: Check #1448 for $232,638.00 recorded as dated/issued to Best Roofing.
The records therefore show a transaction that passed through multiple management and Board approvals over several weeks.
Why was the payment recorded differently?
Castle’s accounting records assigned the two payments to different accounts:
| Accounting record | $232,638.00 check | $124,272.72 payment |
|---|---|---|
| Bank account | MY5-UBS Reserve Acct | MY5-UBS SIRS RES |
| GL account | #900104 | #305655 |
| Description | Special Projects | Contract Liability – CY SIRS Expenses |
| Supporting document | Castle Group Check Request | Falcon-approved payment application |
Other documented Best Roofing payments for this roof project, as you will see below, with invoices dated after January 1, 2025, were recorded under GL #305655 and associated with the SIRS reserve account. The $232,638.00 check was the exception. It was the one and only payment to Best Roofing for this roof replacement project assigned to GL 900104. WHY?
The account classification was questioned internally
A February 2025 exchange between Board President Stewart Glass and Assistant Property Manager Helen Martinez concerned the account used for the $232,638.00 transaction.
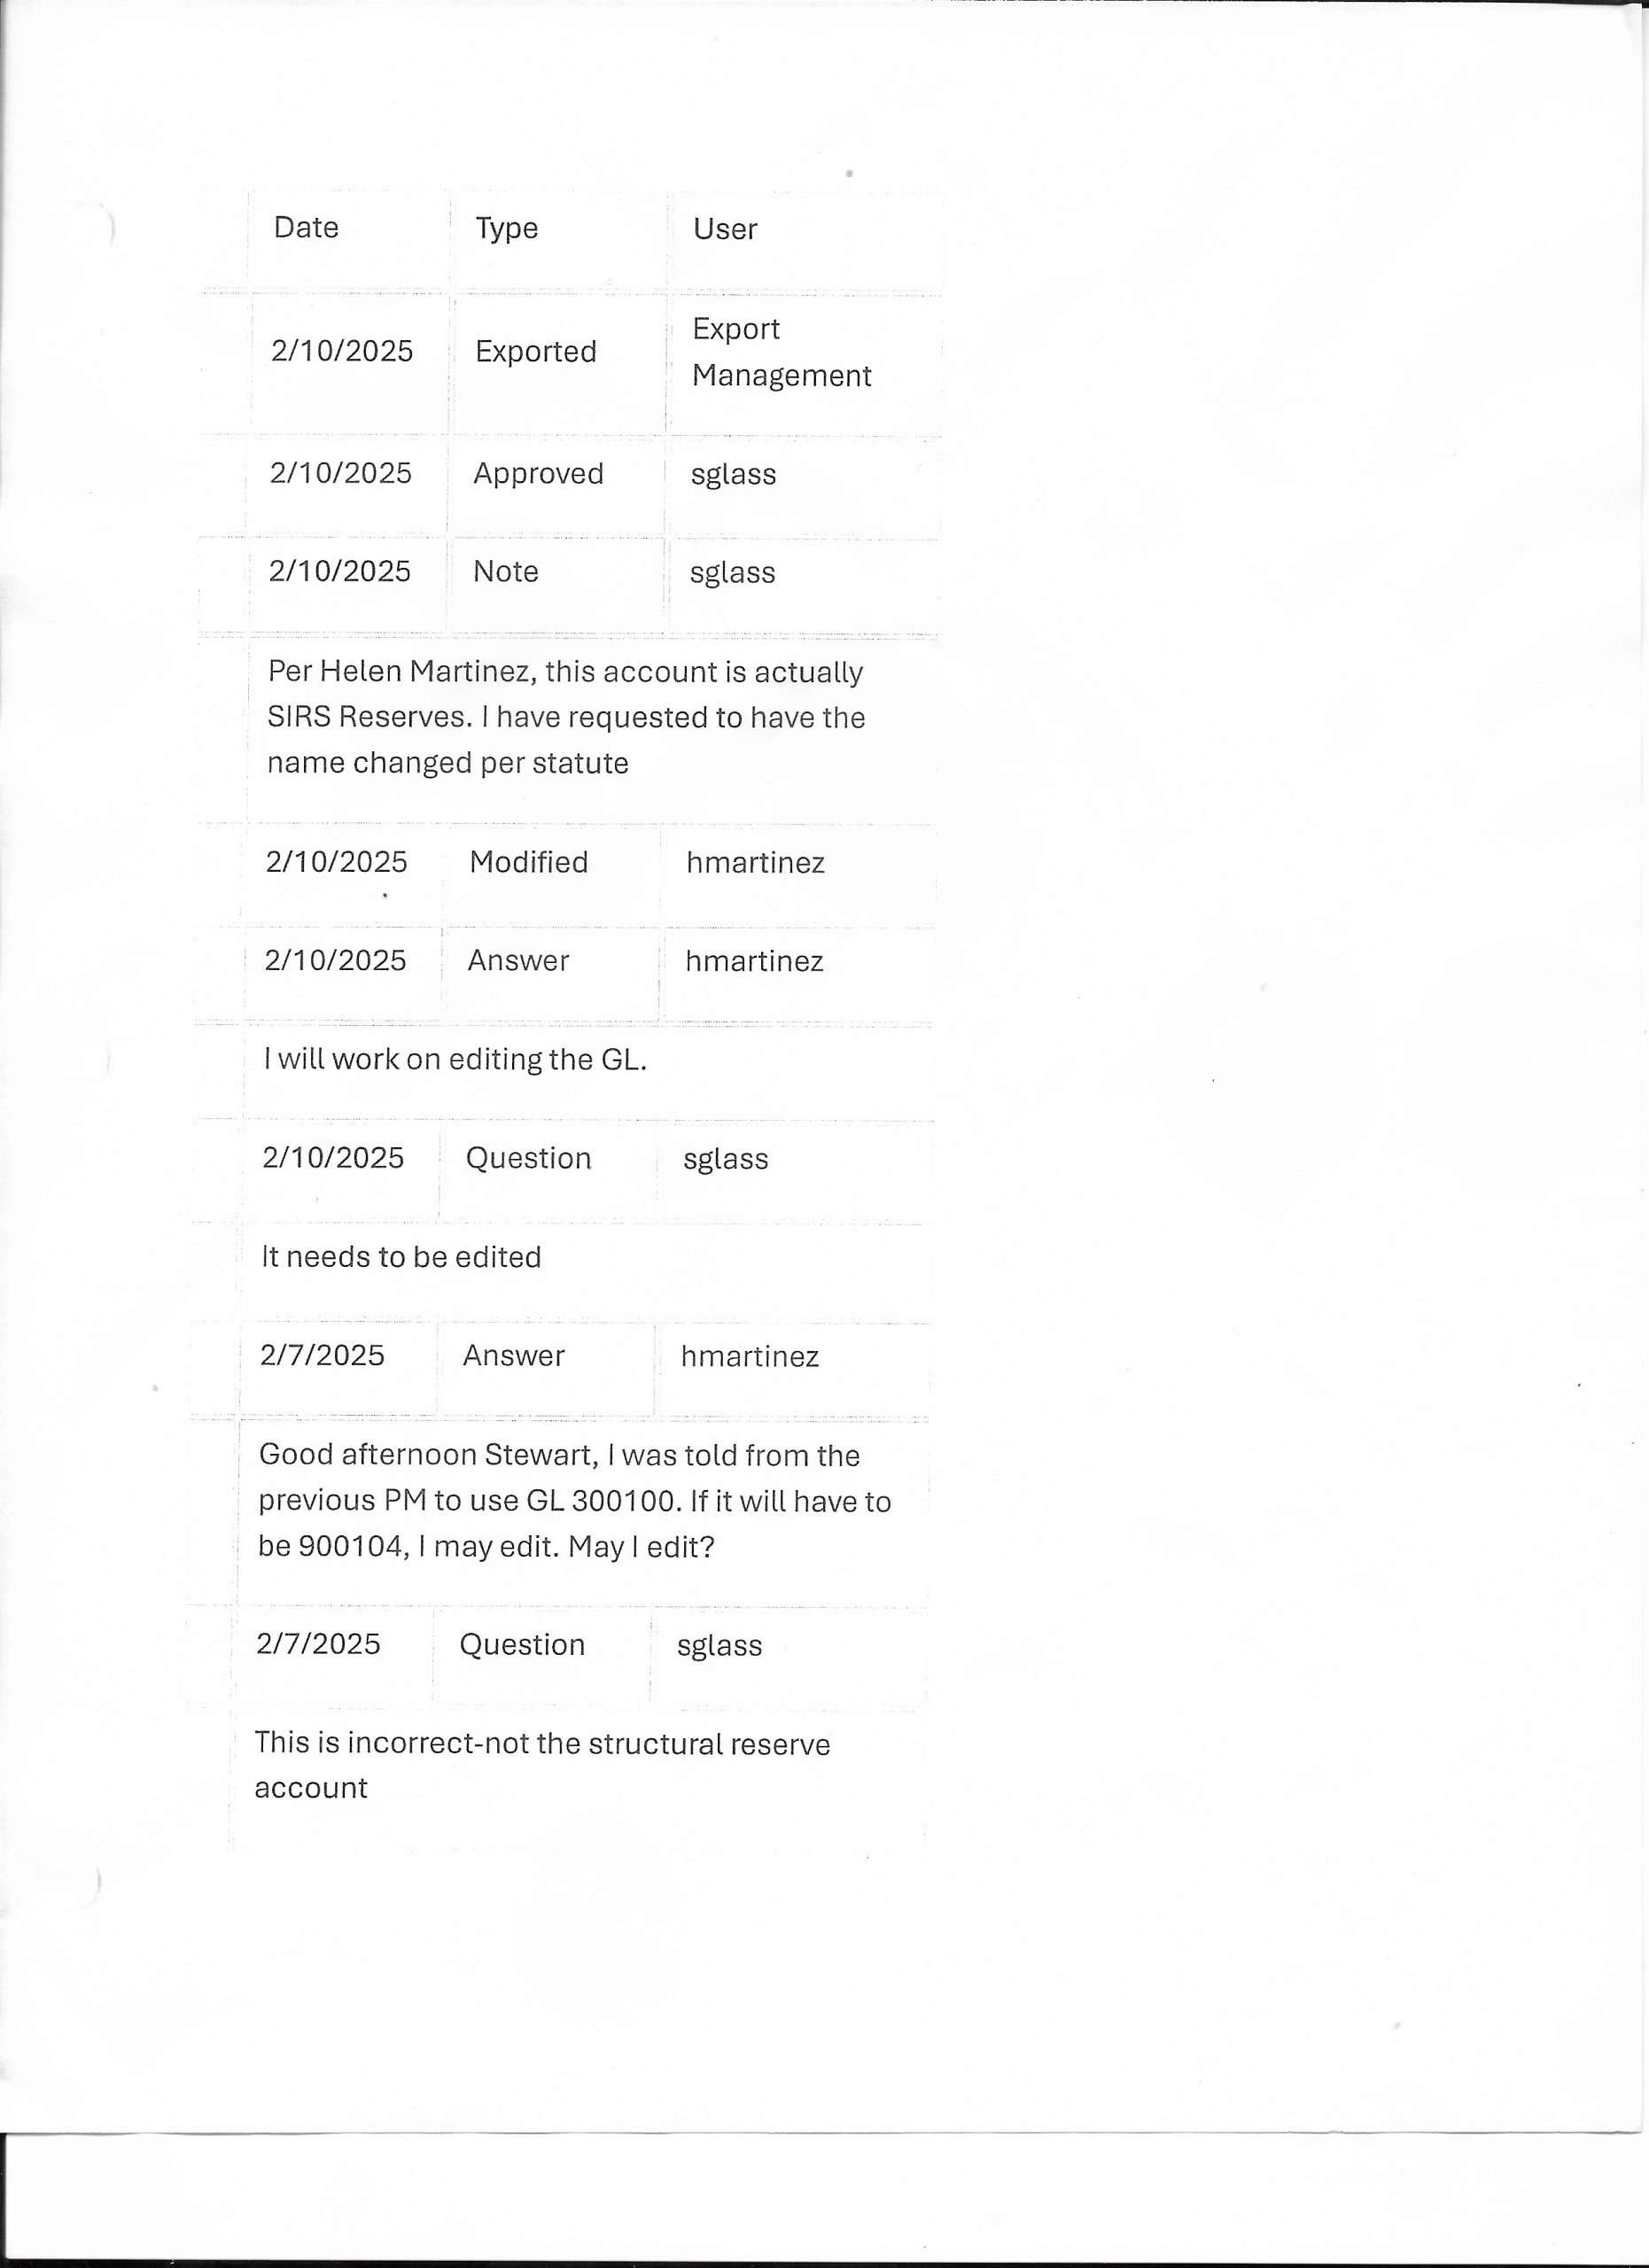
Martinez explained that the previous Property Manager, Liran Shahar, had instructed her to use GL #300100. She then wrote, “If it will have to be 900104, I may edit. May I edit?” Her wording indicates that she understood GL #900104 was to be used instead of GL #300100.
Glass responded, “This is incorrect—not the structural reserve account.” Martinez replied, “I will work on editing the GL.”
Glass subsequently stated “Per Helen Martinez, this account is actually SIRS”.
Why was this payment treated differently? What justified recording it under GL #900104, “Special Projects,” rather than GL #305655, “Contract Liability – CY SIRS Expenses”?
Glass said it is “not the structural reserve account”. In that case, what account is GL #900104??
3. The Check’s Return and the Conflicting Explanations
Owners began asking questions in April 2025. On April 9, Assistant Property Manager Helen Martinez was questioned about the Check Request bearing her signature. She said she did not remember signing it and explained that she signed any document when asked. The following day, Property Manager Michael Alvira was questioned about the payment. After declining to answer without a written request, he received one on April 11 seeking an explanation and documentation concerning the check’s alleged return. At the May Board meeting, Alvira acknowledged that he had not responded to the written request. When asked to explain, all he said was that he had “given it to the lawyer.” Whose lawyer? We don’t know.
The May 7 letter from Association counsel
On May 7, 2025, attorney Marc A. Smiley, writing on behalf of the Association and its Board, stated that the Check Request and check had been “processed and sent … in error.” The letter further stated that Best Roofing had never deposited the check, that it was returned and hand-delivered to Castle Group’s accounting department, and that Castle advised the Association that returned checks were voided and shredded under its standard procedure.
Two different accounts of the check’s return
At the May 2025 Board meeting, Stewart Glass said Best Roofing realized the check had been issued in error and returned it by courier on February 28. According to his account, the check was delivered to Laura, the Front Desk Manager, placed in a drawer, and reportedly forgotten by her for approximately three weeks. Glass said there had been no telephone call from Best Roofing advising us that they received an “unwanted” check. They just hired a courier to deliver it.
In a November 12, 2025, message to owners, Glass gave a different account. He stated that Best Roofing had immediately called the Assistant Manager (Helen Martinez), that the check was voided, and that the supervisor of the Best Roofing project team then hand-delivered it to the Front Desk.
Ms. Martinez has been reassigned, not here to respond.
The accounts differ on a key point: the May account said there had been no telephone call, while the November account said Best Roofing had called immediately. They also describe the check’s return differently.
An unopened envelope without a postage stamp, just bearing a note saying the date February 28 was shown to owners on July 2, 2025, in response to a records request. No explanation as to how Best Roofing would know that there is an “unwanted” check in the envelope they returned.
4. The CastleClick Record Changed
CastleClick initially showed Check #1448 as issued on February 26, 2025. Months later, the date disappeared and the status changed to “Payment is Pending.” Subsequently, the check/payment record no longer appeared in CastleClick at all.
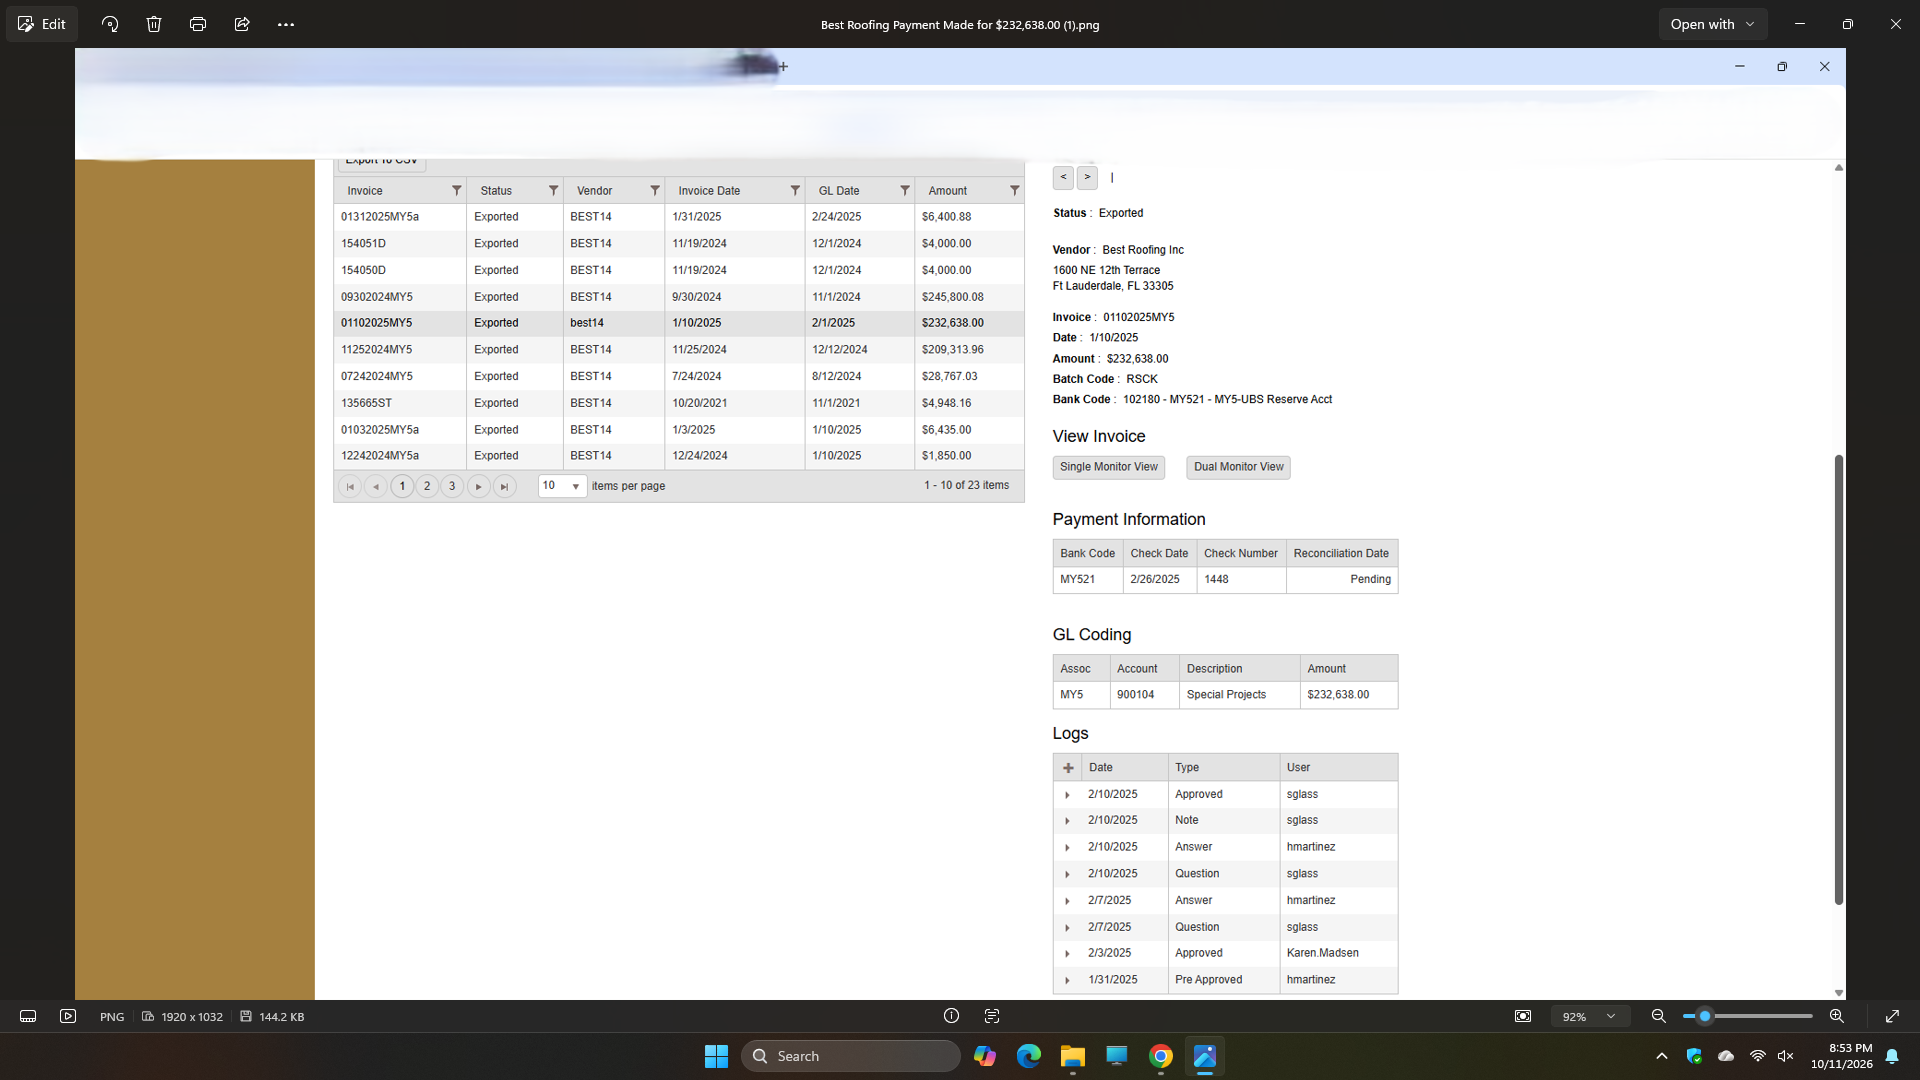
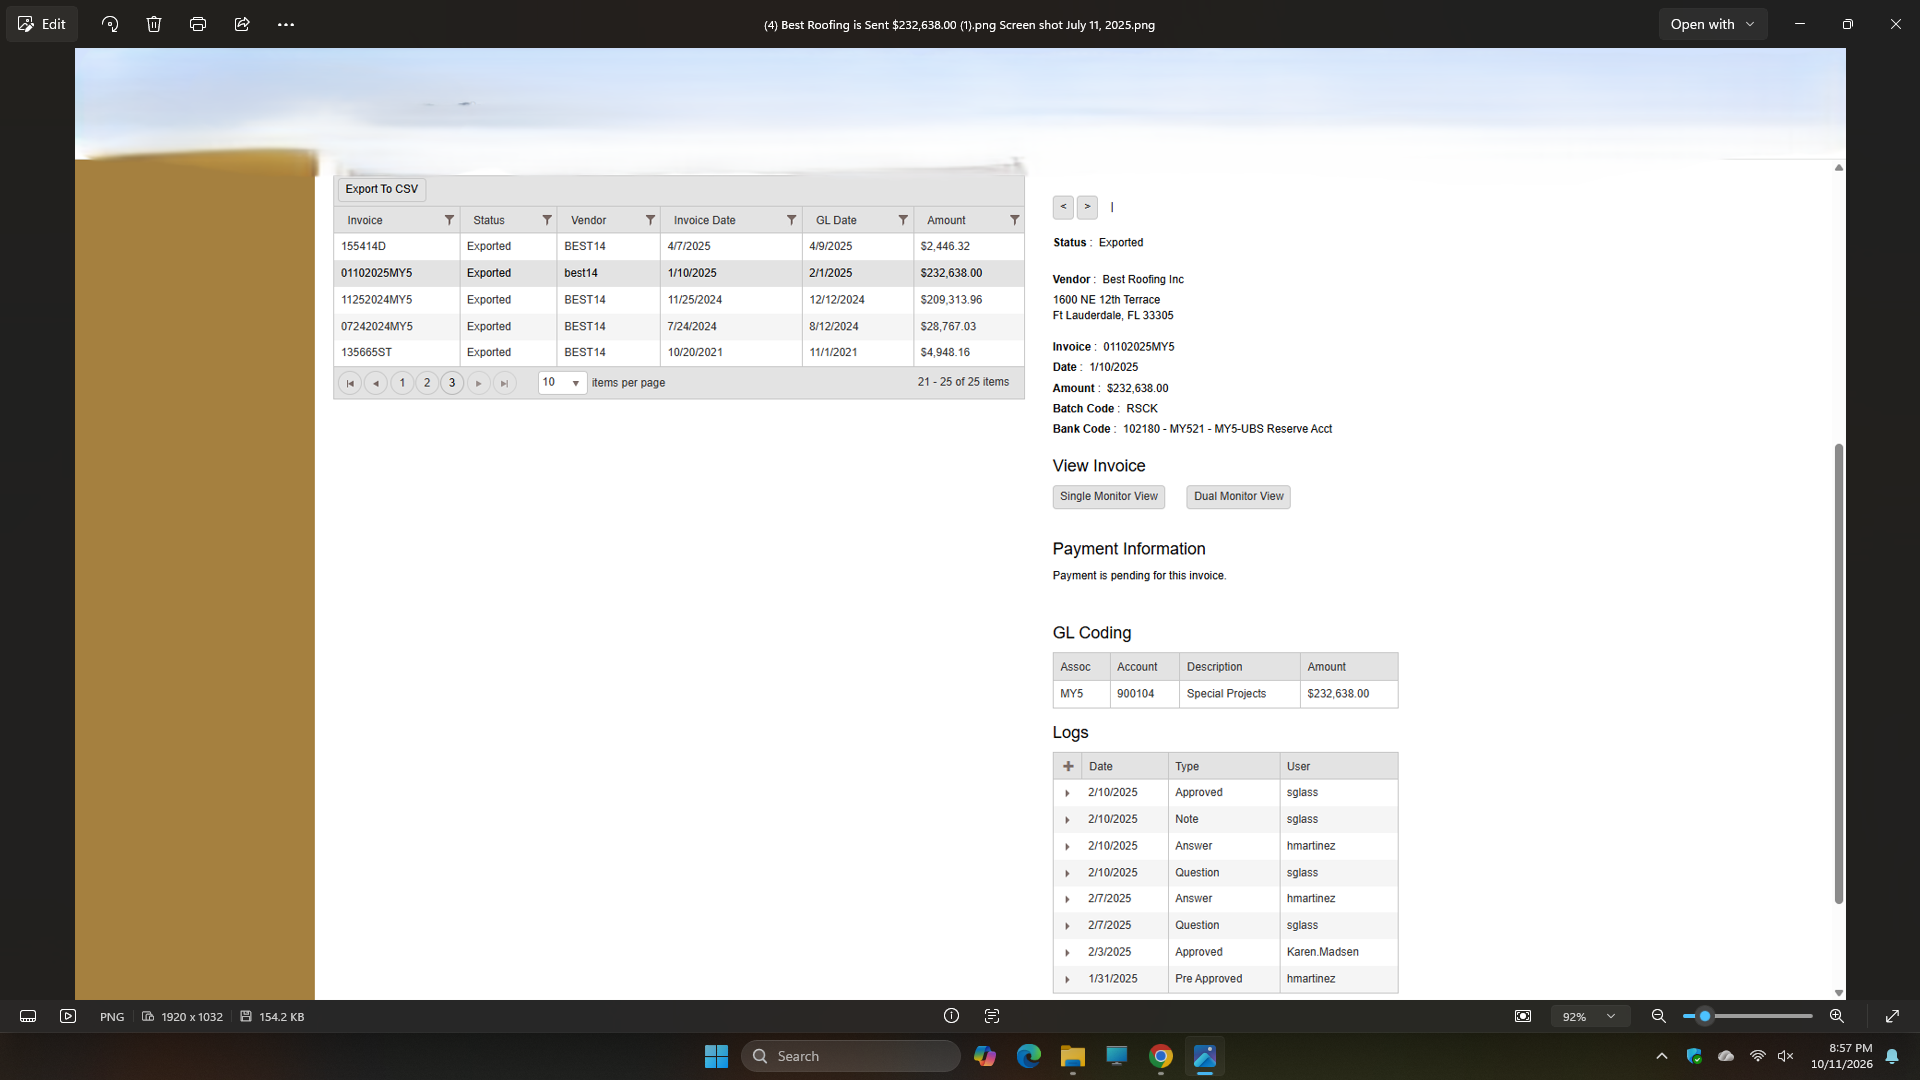
Issued. Then “Payment Pending.” Then no visible record.
The records available for this review do not explain who made these changes, when they were made, or why.
5. What Remains Unanswered
The records presented on this page document a troubling sequence: a $232,638.00 contractual deduction was followed by a payment request for the identical amount; the request passed through multiple management and Board approvals; the payment was recorded differently from the other documented Best Roofing payments; and the explanations of the check’s return differed. CastleClick’s record subsequently changed from “issued” to “Payment Pending,” and eventually disappeared.
These facts do not, by themselves, establish what ultimately happened to the money. They do, however, make a documented accounting reconciliation essential. The claim that the check was issued in error is not a substitute for records demonstrating how the transaction was resolved.
The central questions remain unanswered: Why was this payment handled differently? What records establish that the check was voided and the transaction properly reversed or otherwise reconciled? Why did the explanations of the check’s return differ, and why did its CastleClick record disappear?
The records for other Best Roofing payments for this roof project tell a consistent story. All the payments shown here for invoices dated after January 1, 2025—including the legitimate $124,272.72 payment—were recorded as you saw in the table above. Except for the $232,638.00 payment.
Have the Requested Records Actually Been Provided?
On March 13, 2026, Ms. Wright stated that invoices and accounting information had already been provided and concluded, “the Association considers this matter addressed.”
On March 16, Matthew Roth identified a specific discrepancy: the other documented Best Roofing payments, as you saw above, including the $124,272.72 final payment, appeared under GL #305655, while the $232,638.00 payment appeared under GL #900104. Ms. Wright’s explanation does not withstand comparison with the accounting records. The $232,638.00 check is the only documented Best Roofing payment after January 1, 2025, recorded under GL #900104; every other documented payment was recorded under GL #305655. What accounts for this exception, and where is the accounting documentation that explains it? Board and Management have not explained this discrepancy.
Despite repeated requests, postponements, and records-inspection meetings attended by Roth and Henry Kaplan, Management has not provided the specific records needed to explain this discrepancy. The question remains straightforward: Why was the $232,638.00 check treated differently from every other documented Best Roofing payment after January 1, 2025, and where is the accounting documentation that justifies that difference?